2025 at a glance


Our sustainability commitments matter. They protect the environment, support communities, reduce risk, and ensure the company remains viable and competitive in a world where responsible mining is non‑negotiable.
Revenue

(2024: $5.8bn)

Gold production

(2024: 2.66Moz)

Gold Mineral Reserve

(2024: 31.2Moz)

People employed

employees and contractors on average

(2024: 36,496)▴

Total recordable injury frequency rate (TRIFR)

(2024: 0.98)

Training and development expenditure

(2024: $7.99m)◊

Salaries, wages and benefits paid to employees

(2024: $796m)

Community investment

(2024: $20.56m)◊

Expenditure with local suppliers

(2024: $4.26bn (92%))◊

Grievances resolved

(2024: 93%)◊

Reportable environmental incidents

(2024: 1)◊

Cumulative amount of land rehabilitated

(2024: 4,271ha)

Renewable energy supply

(2024: 6.6%)

Scope 1 and Scope 2 greenhouse gas (GHG) emissions

(2024: 1.473Mt)◊

Employees that completed ethics training*

(2024: 5,697)◊

Payments to government ∧

(2024: $1.03bn)◊

Security personnel trained on human rights policies

(2024: 100%)◊

◊ Excludes Centamin

▲ Excludes Kibali

* Excludes contractors

∧ Refer to ESG Data Workbook for breakdown

Leadership


Determining materiality


We are cognisant that material sustainability issues change over time (dynamic materiality), and we will continue to monitor the broader range of issues, including emerging issues.

While we have grouped the sustainability issues identified into related environment, social, governance and economic topics, we recognise that these issues are deeply interrelated and inter-dependent and should be considered and managed accordingly.

The Company’s double materiality assessment is integrated into the Enterprise Risk Management (ERM) framework ensuring the Company considers a comprehensive view of risks and opportunities that may affect not only its financial outcomes but also its broader societal and environmental responsibilities.

Our 2025 materiality assessment included detailed interviews with key internal and external stakeholders, and considered new and emerging disclosure regulations including GRI and SASB. Extractives and mineral processing are among the first industries scheduled for updated SASB-aligned guidance, with new emphasis expected in areas such as biodiversity, water use, tailings, land disturbance, workforce conditions, closure planning and community impacts. These developments informed our framing of material sustainability issues this year, ensuring that our prioritisation reflects future regulatory direction rather than only historical expectations.

Impact materiality

Whether a matter is material from an impact perspective, that is, whether AngloGold Ashanti’s activities have a material actual or potential impact, positive or negative, on people, society and/or the environment over the short, medium or long term.

Financial materiality

Whether a matter is material from a financial perspective and whether it triggers potential or actual financial effects on AngloGold Ashanti, that is, whether it leads to risks or opportunities that influence or could influence future cash flows and the enterprise value of the Company in the short, medium or long term.

Initial benchmarking involved a thorough review of global standards and voluntary compacts to which we subscribe and align with, peer practices and feedback from ratings agencies, as well as prior year assessments.This benchmarking ensured that the issues considered are relevant, comprehensive and reflect both industry best practice and stakeholder expectations. We then arrived at a comprehensive long list of sustainability topics relevant to AngloGold Ashanti’s footprint and industry context, which we carefully refined to identify 33 issues that are relevant to our industry and sector.

We held structured interviews with internal and external stakeholders/leaders to understand:

  • Strategic priorities
  • Operational challenges and dependencies
  • Regional sustainability expectations
  • Emerging risks and opportunities

This process resulted in a refined list of 21 material sustainability issues, including new issues, strengthened definitions, and determining how issues influence our ability to create, sustain, or potentially erode social, environmental, and economic value from both an impact and financial materiality perspective.

Finally, members of executive and senior management were asked to rank issues from the perspective of both impact and financial materiality, based on our definitions (alongside). Respondents were also asked to indicate the time horizon –short, medium and long term – associated with impacts and, for financial materiality, whether the issue was primarily a risk or an opportunity.

These issues were then reviewed by the internal sustainability team. The ranking was adjusted to reflect broader industry sustainability issues and issues raised by stakeholders. These results were analysed and combined with internal insights to determine the 17 material sustainability issues for 2025.

Our commitments


Case studies


Assurance


As a member of the International Council on Mining & Metals (ICMM), AngloGold Ashanti plc is committed to obtaining independent external assurance over its conformance with the ICMM Mining Principles, including specified disclosures presented in its 2025 Sustainability Report
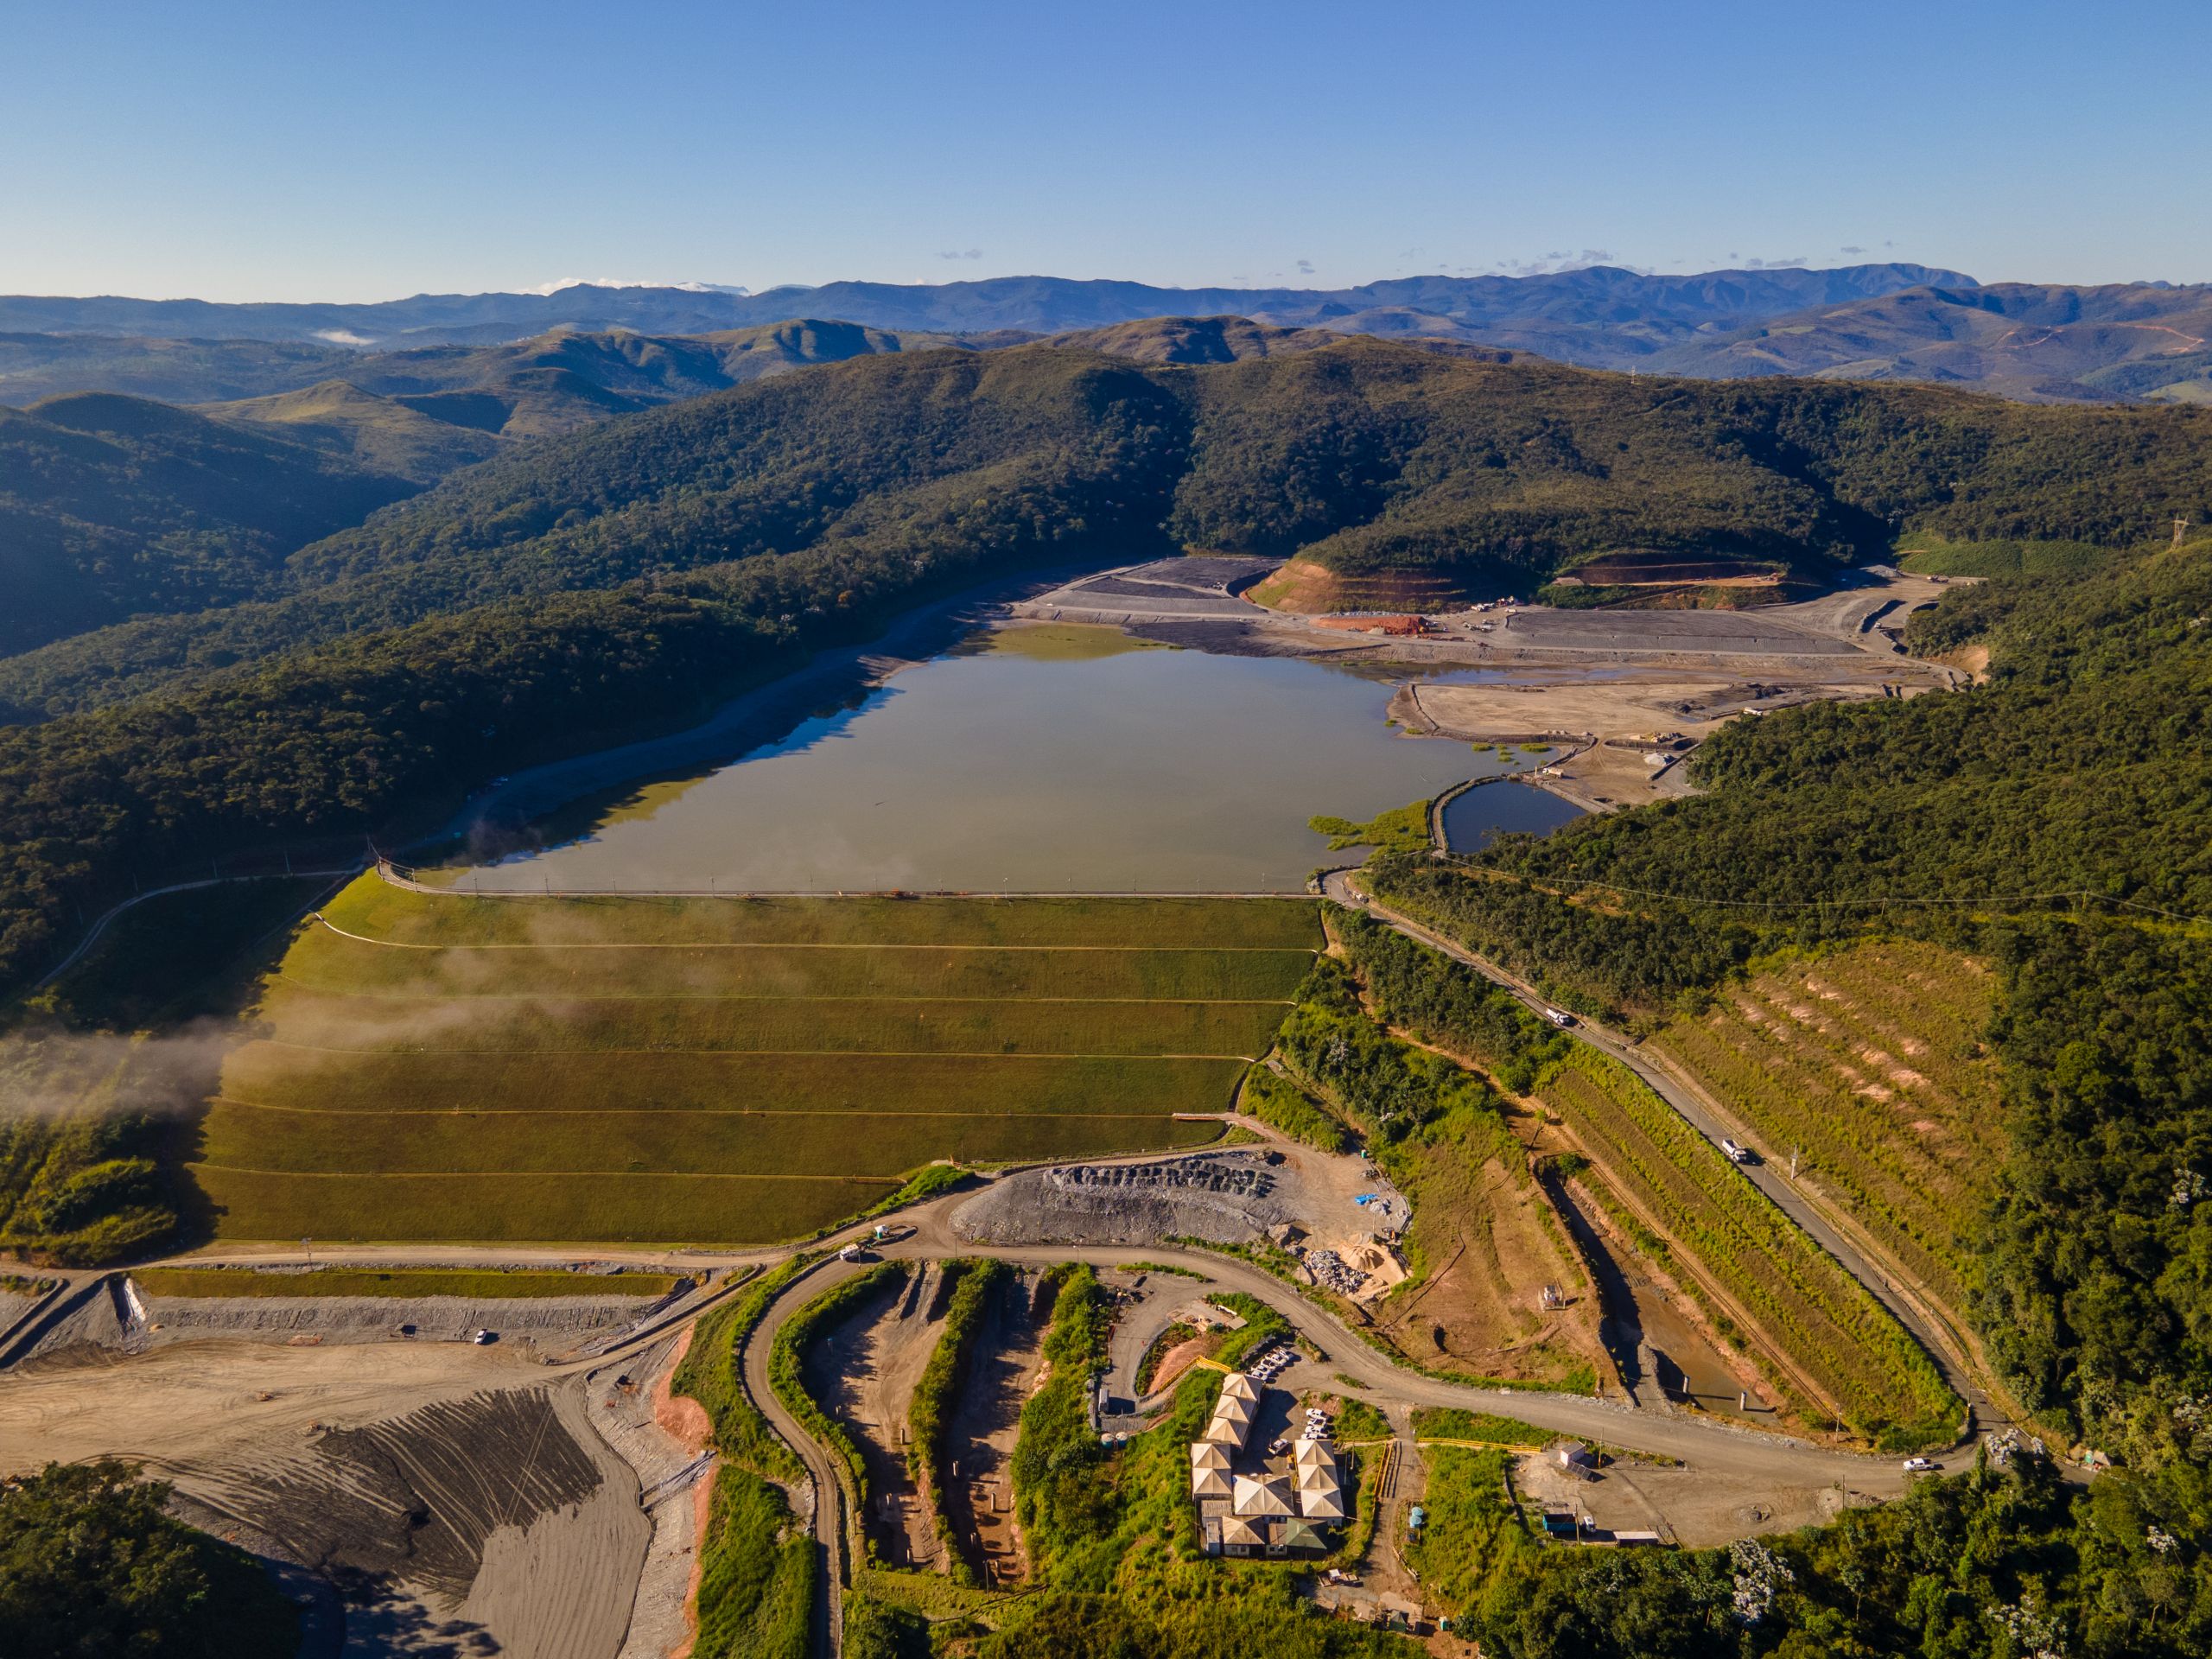
This residue is usually composed of finely milled ore, water and trace quantities of metals and additives used in processing. While some tailings residue may be placed as backfill (that is, returned to the excavated area underground in carefully contained paddocks), most residue is deposited in surface tailings storage facilities (TSFs).

AngloGold Ashanti has developed a comprehensive and holistic approach to tailings management and remains committed to the industry’s transformative improvements in tailings governance, accountability and transparency.

We seek to comply with local and international tailings management standards and best practice, including the GISTM.

Tailings management system helps ensure that risks related to TSFs are identified, recorded and mitigated.

Mitigation measures and performance are tracked and communicated at all levels in the business, and our Board and Executive members are kept informed of the status of our TSFs through regular reporting.

Governance structures ensure resources and actions are in place to manage TSFs and to comply with legislation and international and industry standards.

Our commitment

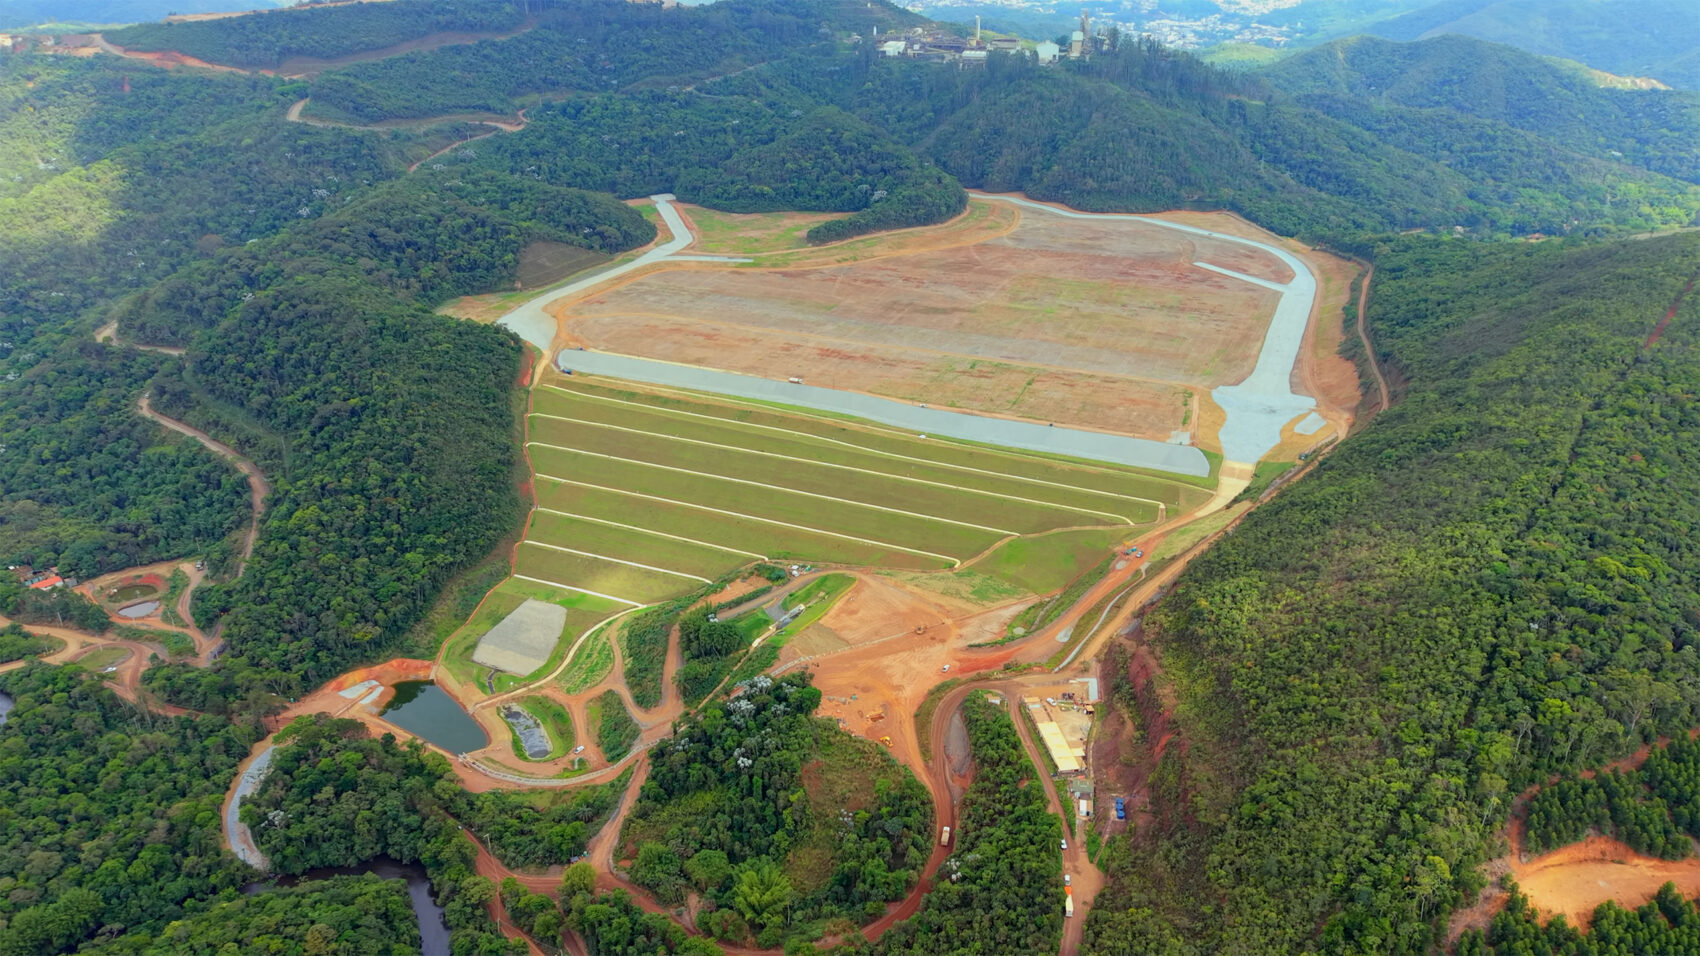
We are committed to the responsible governance and management of our TSFs throughout their life cycle, from design to closure and post closure.

As a member of the ICMM, we subscribed to and committed to implementing the GISTM at all our TSFs, achieving substantial conformance by, and issuing a Declaration of Conformance in August Our Statement of Commitment to the GISTM may be found on our website. The GISTM complements our own Tailings Management Framework that sets our principles, standards, guidelines and accountabilities for the construction, management, and oversight of TSFs, and our compliance with national standards and legislation.

  • Continued progress towards achieving full conformance with the GISTM
  • Integration of Sukari mine’s TSFs into our oversight and management systems
  • Continued journey to minimising risk at all facilities to ALARP (as low as reasonably practicable), with priority actions ongoing at Siguiri and Obuasi
  • Continue to target best practice and risk mitigation

Performance in 2025

Combining industry best practice and decades of institutional experience, AngloGold Ashanti focuses on the sound management of all phases of the TSF life cycles from planning to closure.

Our tailings management protocol is guided by our Tailings Management Framework and based on a four-layered assurance system aimed at achieving zero harm to people and the environment.

AngloGold Ashanti manages 24 TSFs, 13 of which are active, with the remainder in the process of closure or removal by re-mining. Safe closure has also been achieved for several historical TSFs at our operations.

Our Tailings Management Standard sets the mandatory requirements for the management of TSFs. Adopting a risk-based approach, the standard requires sites to:

  • Identify and document the relevant legislative and regulatory requirements and to review applicable TSF compliance requirements annually
  • Maintain a life-of-mine tailings storage plan that is updated concurrently with the life of mine production plans
  • Develop, implement, and maintain integrated plans, procedures, practices, and assign responsibilities covering the design, approvals, construction, operation, and closure of TSFs
  • Define and document the responsibilities of all employees and contractors involved with tailings management and validate that they are authorised and competent to conduct their work effectively
  • Collect, monitor and analyse data to assess the stability and integrity of each TSF and update stability analyses annually
  • Develop site-specific closure criteria and closure plans for each TSF
  • Prepare and document detailed emergency preparedness and response plans for potential TSF failures as well as carry out annual testing of the TSF emergency response plan

The careful management and monitoring of TSFs using a four-tiered assurance system has allowed us to maintain a strong track record in managing an international portfolio of different types of TSFs. Importantly, TSF management is overseen by the Board via the SES Committee and Executive Committee.

Responsibilities of teams as per our four-layered assurance system

  • TSF operator/superintendent manages the day-to-day operation
  • Plant or process manager considered ‘owner’ of TSF and is responsible for implementing requirements of the TSF operating manual
  • Provides technical guidance to operations
  • Conducts quarterly inspections of active TSFs
  • Monitors implementation of recommended actions
  • Custodian of Tailings Management Framework
  • Conducts formal TSF audits annually or biennially
  • TSF review for projects and for mergers and acquisitions
  • Independently reviews tailings facility as per the GISTM

Information relating to the status of each of our TSFs and our conformance to the GISTM is disclosed on our website

AngloGold Ashanti supports and is committed to achieving full conformance with of the GISTM, the global benchmark for achieving strong social, environmental and technical outcomes by elevating accountability to the highest organisational levels.

With the ultimate goal of zero harm to people and the environment, the standard strengthens tailings facility life cycle practices — from site selection, design and construction, through management and monitoring, to closure and post-closure — adding requirements for independent oversight, transparency and public disclosure.

We have made significant progress toward full conformance to the GISTM’s principles and are able to report substantial conformance as indicated in the table below.

The GISTM complements our own Tailings Management Framework that sets our principles, standards, guidelines and accountabilities for the construction, management, and oversight of TSFs, and our compliance with national standards and legislation.

Since the GISTM was finalised in 2020, we have developed a conformance protocol to meet the standard’s 77 requirements. These conformance efforts have strengthened our internal tailings governance structures and systems.

We have appointed External Engineers of Record and Independent Tailings Review Boards at all our operations, embraced new technologies and processes and undertaken additional precautionary measures to reduce risk and meet regulatory and other requirements.

Detailed information relating to each of our tailings facilities and progress summaries for each of our TSFs are published on our website.

  • Ensuring the safety and integrity of tailings storage facilities
  • Securing and maintaining regulatory compliance, including environmental licences and permits
  • Preparing for and managing risk and emergencies to minimise impacts on people and operations
  • Ensuring water security and stewardship
  • Managing nature and biodiversity, including land use, rehabilitation and responsible closure

For more information on principal risks see the 2025 Annual Report

  • Failure to maintain integrity of tailings storage facilities
  • Failure to maintain social licence to operate
  • Failure to maintain sufficient resilience to
    external financial drivers
  • GRI 14.6.1: Compliance with international standards on tailings management
  • GRI 14.6.2: Tailings disposal methods
  • SASB EM-MM-150a.5: Total weight of tailings produced
  • SASB EM-MM-540a.1: Tailings storage facility inventory table
  • SASB EM-MM-540a.2: Tailings management systems and governance structure used to monitor and maintain the stability of TSFs
  • SASB EM-MM-540a.3: Approach to emergency preparedness and response plans for TSFs
  • ICMM Mining Principle 6-6.3: Environmental performance: Design, construct, operate, monitor and decommission tailings disposal/ storage facilities using comprehensive, riskbased management and governance practices.
  • WGC Responsible Gold Mining Principle 8: Environmental stewardship: We will ensure that environmental responsibility is at the core of how we work.
        PRINCIPLES
Country Operation TSF GISTM Classification 1 2 3 4 5 6 7 8 9 10 11 12 13 14 15
Australia Sunrise Dam CTD High Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Australia Sunrise Dam TSF 1 Significant Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Australia Tropicana Tropicana Very High Meet Meet Meet Meet Meet Meet Meet Meet Meet Partial Meet Meet Meet Meet Meet
Egypt Sukari TSF 1 Very High Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Egypt Sukari TSF 2 Significant Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Tanzania Tanzania Geita Extreme Meet Meet Meet Meet Partial Meet Meet Meet Meet Meet Meet Meet Partial Meet Meet
Tanzania Tanzania Old Low Meet Meet Meet Meet Partial Meet Meet Meet Meet Meet Meet Meet Partial Meet Meet
Guinea Guinea Siguiri Extreme Meet Partial Meet Partial Partial Meet Partial Meet Meet Partial Meet Meet Partial Meet Meet
Ghana Iduapriem GTSF Very High Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Partial Meet Meet
Ghana Iduapriem OTSF | ITSF Very High Meet Partial Meet Partial Partial Meet Partial Meet Meet Partial Meet Meet Partial Meet Meet
Ghana Iduapriem BTSF High Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Partial Meet Meet
Ghana Obuasi Pompora Extreme Meet Partial Meet Partial Partial Meet Partial Meet Meet Partial Meet Meet Partial Meet Meet
Ghana Obuasi Kokotesua Extreme Meet Partial Meet Partial Partial Meet Partial Meet Meet Partial Meet Meet Partial Meet Meet
Ghana Obuasi STSF Very High Meet Partial Meet Partial Partial Meet Meet Meet Meet Partial Meet Meet Partial Meet Meet
Ghana Obuasi Biox High Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Partial Meet Meet
Argentina CVSA Diq. Colas High Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Brazil CDS CDS 2 Extreme Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Brazil CDS Pilha Sape Very High Meet Meet Meet Partial Meet Meet Meet Meet Meet Meet Meet Meet Partial Meet Meet
Brazil CDS Grota 1 Low Meet Meet Meet Partial Partial Meet Partial Meet Meet Partial Meet Meet Partial Meet Meet
Brazil Cuiaba Cuiaba Extreme Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Brazil Cuiaba Open Pit CB High Meet Meet Meet Partial Partial Meet Partial Meet Meet Partial Meet Meet Partial Meet Meet
Brazil Queiroz Calcinados Extreme Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Brazil Queiroz Cocoruto Extreme Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet
Brazil Queiroz Rapaunha Extreme Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet Meet

* As at 5 August 2025 (updates forthcoming in June and Dec 2026)

  • Meets
  • Partially Meets (Work in progress to achieve conformance)
  • Does Not Meet
  • CDS = Córrego do Sítio
  • TSF = Tailings Storage Facility
  • BTSF = Beposo TSF
  • GTSF = Greenfields TSF
  • OTSF | ITSF = Old TSF / Interim TSF
  • STSF = South TSF
  • Principle 1: Respect the rights of project-affected people and meaningfully engage them at all phases of the tailings facility lifecycle, including closure.
  • Principle 2: Develop and maintain an interdisciplinary knowledge base to support safe tailings management throughout the tailings facility lifecycle, including closure.
  • Principle 3: Use all elements of the knowledge base – social, environmental, local economic and technical – to inform decisions throughout the tailings facility lifecycle, including closure.
  • Principle 4: Develop plans and design criteria for the tailings facility to minimise risk for all phases of its lifecycle, including closure and post closure.
  • Principle 5: Develop a robust design that integrates the knowledge base and minimises the risk of failure to people and the environment for all phases of the tailings facility lifecycle, including closure and post-closure.
  • Principle 6: Plan, build and operate the tailings facility to manage risk at all phases of the tailings facility lifecycle, including closure and post-closure.
  • Principle 7: Design, implement and operate monitoring systems to manage risk at all phases of the facility lifecycle, including closure.
  • Principle 8: Establish policies, systems and accountabilities to support the safety and integrity of the tailings facility.
  • Principle 9: Appoint and empower an Engineer of Record.
  • Principle 10: Establish and implement levels of review as part of a strong quality and risk management system for all phases of the tailings facility lifecycle, including closure.
  • Principle 11: Develop an organisational culture that promotes learning, communication and early problem recognition.
  • Principle 12: Establish a process for reporting and addressing concerns and implement whistleblower protections.
  • Principle 13: Prepare for emergency response to tailings facility failures.
  • Principle 14: Prepare for long-term recovery in the event of catastrophic failure.
  • Principle 15: Publicly disclose and provide access to information about the tailings facility to support public accountability.

The Ghana Minerals Commissions granted approval for the Obuasi mine to commence construction of its new Dokyiwa Flotation Tailings Storage Facility. The Ghana EPA also renewed the environmental permits for the Obuasi Redevelopment Project, BIOX TSF and water infrastructure projects.

The EPA is conducting a year-long study at Binsere to assess the extent of environmental and health impacts of the BIOX TSF on the community. Expected to conclude during 2026, the EPA has already determined that community members living within 100m of the facility are too close and directed that they be relocated for their safety.

Obuasi will develop a resettlement plan for residents within the 100m buffer zone and, in collaboration with community leaders and the Municipal Assembly, will enforce a ‘No Development’ area within the 100m buffer zone. Drone footage of the area will highlight community assets within the buffer zone and serve as a reference for determining compensation.

Following the Tanzanian Ministry of Water’s concern about evaporator trials for managing excess process water from the Geita TSF, a multi-disciplinary workshop involving the National Environmental Management Council, the Ministry of Water and the Tanzania Meteorological Authority was convened. This led to in-principle approval for a six-month trial, subject to the formality of a justification note seeking approval from the Chief Inspector of Mines. On conclusion of the trial, Geita will submit a technical report detailing the key findings and the system’s performance. If proceeding with a permanent installation, the mine would have to undertake a full EIA.

Designs are in progress for a new TSF at Siguiri. This will allow the transition and closure of the existing TSF. Work on this is expected to be executed over the 2026—2028 period.

Looking ahead

Focus areas for 2026 include (but are not limited to):

  • The remediation and closure of TSF 1 at Siguiri, with the design and construction of a new TSF 2
  • The transition from the STSF at Obuasi to the new DTSF, allowing the STSF to enter operational closure
  • Projects to advance the removal and closure of Kokoteasua and Pompora Tailings facilities at Obuasi
  • Continued progress towards achieving full conformance with the GISTM

Disclaimer

This webpage does not purport to be a complete summary of the applicable underlying report and is qualified in its entirety by reference to the applicable underlying report. This webpage should be read in conjunction with the applicable underlying report, including the qualifications and limitations described therein, as there may be information in the applicable underlying report that may be important.

All Mineral Resource and Mineral Reserve information should be read in conjunction with Item 4D. Mineral Resource and Mineral Reserve in AngloGold Ashanti’s annual report on Form-20F for the fiscal year ended 31 December 2025, as filed with the U.S. Securities and Exchange Commission, as well as AngloGold Ashanti’s 2025 Mineral Resource and Mineral Reserve Report.

Forward-looking statements

Certain statements contained in this webpage, other than statements of historical fact, including, without limitation, those concerning the economic outlook for the gold mining industry, expectations regarding gold prices, production, mine life, total cash costs, all-in sustaining costs, cost savings and other operating results, return on equity, productivity improvements, growth prospects, preliminary financial and production metrics for in-process projects, the ability to convert Mineral Resource into Mineral Reserve and replace Mineral Reserves net of depletion from production and outlook of AngloGold Ashanti’s operations, individually or in the aggregate, including the achievement of project milestones, commencement and completion of commercial operations of certain of AngloGold Ashanti’s exploration and production projects and the completion of acquisitions, dispositions or joint venture transactions, AngloGold Ashanti’s liquidity and capital resources and capital expenditures and the outcome and consequences of any potential or pending litigation or regulatory proceedings or environmental, health and safety issues, are forward-looking statements regarding AngloGold Ashanti’s financial reports, operations, economic performance and financial condition.

These forward-looking statements or forecasts are not based on historical facts, but rather reflect our current beliefs and expectations concerning future events and generally may be identified by the use of forward-looking words, phrases and expressions such as “believe”, “expect”, “aim”, “anticipate”, “intend”, “foresee”, “forecast”, “predict”, “project”, “estimate”, “likely”, “may”, “might”, “could”, “should”, “would”, “seek”, “plan”, “scheduled”, “possible”, “continue”, “potential”, “outlook”, “target” or other similar words, phrases, and expressions; provided that the absence thereof does not mean that a statement is not forward-looking. Similarly, statements that describe our objectives, plans or goals are or may be forward-looking statements.

These forward-looking statements or forecasts involve known and unknown risks, uncertainties and other factors that may cause AngloGold Ashanti’s actual results, performance, actions or achievements to differ materially from the anticipated results, performance, actions or achievements expressed or implied in these forward-looking statements. Although AngloGold Ashanti believes that the expectations reflected in such forward-looking statements and forecasts are reasonable, no assurance can be given that such expectations will prove to have been correct. Accordingly, results, performance, actions or achievements could differ materially from those set out in the forward-looking statements as a result of, among other factors, changes in economic, social, political and market conditions, including related to inflation or international conflicts, the success of business and operating initiatives, changes in the regulatory environment and other government actions, including environmental approvals, fluctuations in gold prices and exchange rates, the outcome of pending or future litigation proceedings, any supply chain disruptions, any public health crises, pandemics or epidemics, the failure to maintain effective internal control over financial reporting or effective disclosure controls and procedures, the inability to remediate one or more material weaknesses, or the discovery of additional material weaknesses, in the Company’s internal control over financial reporting, and other business and operational risks and challenges and other factors, including mining accidents. For a discussion of such risk factors, refer to the Company’s annual report on Form 20-F for the financial year ended 31 December 2025, filed with the U.S. Securities Exchange Commission. These factors are not necessarily all of the important factors that could cause AngloGold Ashanti’s actual results, performance, actions or achievements to differ materially from those expressed in any forward-looking statements. Other unknown or unpredictable factors could also have material adverse effects on AngloGold Ashanti’s future results, performance, actions or achievements. Consequently, readers are cautioned not to place undue reliance on forward-looking statements.

AngloGold Ashanti undertakes no obligation to update publicly or release any revisions to these forward-looking statements to reflect events or circumstances after the date of publication or to reflect the occurrence of unanticipated events, except to the extent required by applicable law. All subsequent written or oral forward-looking statements attributable to AngloGold Ashanti or any person acting on its behalf are qualified by the cautionary statements herein.

NON-GAAP financial measures

This document may contain certain “Non-GAAP” financial measures, including, without limitation, “total cash costs”, “total cash costs per ounce”, “all-in sustaining costs”, “all-in sustaining costs per ounce”, “average gold price received per ounce”, “sustaining capital expenditure”, “non-sustaining capital expenditure”, “Adjusted EBITDA”, “Adjusted net debt (cash)”, “operating cash flow” and “free cash flow”. AngloGold Ashanti utilises certain Non-GAAP performance measures and ratios in managing its business. Non-GAAP financial measures should be viewed in addition to, and not as an alternative for, the reported operating results or cash flow from operations or any other measures of performance prepared in accordance with IFRS. In addition, the presentation of these measures may not be comparable to similarly titled measures other companies may use. Reconciliations from IFRS to the Non-GAAP financial measures used in this document can be found either in this document, or in AngloGold Ashanti’s Earnings Release for the three months and the year ended 31 December 2025, which is available on AngloGold Ashanti’s website, or in its annual report on Form 20-F for the financial year ended 31 December 2025 as filed with 
the SEC.

2025 Mineral Resource and Mineral Reserve information

The Mineral Resource and Mineral Reserve stated herein were prepared in compliance with Subpart 1300 of Regulation S-K (17 CFR § 229.1300) (“Regulation S-K 1300”). Refer to Item 1300 (Definitions) of Regulation S-K for the meaning of the terms used in AngloGold Ashanti’s Mineral Resource and Mineral Reserve reporting. The Mineral Resource and Mineral Reserve represent the amount of gold, copper, silver, sulphur and molybdenum estimated at 31 December 2025 and are based on information available at the time of estimation. Such estimates are, or will be, to a large extent, based on the prices of the respective commodities and interpretations of geologic data obtained from drill holes and other exploration techniques, which data may not necessarily be indicative of future results. The Mineral Resource and Mineral Reserve estimates are published at 31 December 2025, taking into account economic assumptions, changes to future production and capital costs, depletion, additions as well as any acquisitions or disposals during 2025. The legal tenure of each material property has been verified to the satisfaction of the accountable Qualified Person and all of the Mineral Reserve has been confirmed to be covered by the required mining permits or there exists a realistic expectation, based on applicable laws and regulations, that issuance of permits or resolution of legal issues necessary for mining and processing at a particular deposit will be accomplished in the ordinary course and in a timeframe consistent with AngloGold Ashanti’s (or its joint venture partners’) current mine plans. For the Mineral Reserve, the term “economically viable” means that profitable extraction or production has been established or analytically demonstrated in, at a minimum, a pre-feasibility study, to be economically viable under reasonable investment and market assumptions. Mineral Reserve is subdivided and reported, in order of increasing geoscientific knowledge and confidence, into Probable and Proven Mineral Reserve categories. Mineral Reserve is aggregated from the Probable and Proven Mineral Reserve categories. Ounces of gold or silver or pounds of copper or sulphur included in the Probable and Proven Mineral Reserve are estimated and reported as delivered to plant (i.e., the point where material is delivered to the processing facility) and exclude losses during metallurgical treatment. In compliance with Regulation S-K 1300, the Mineral Resource herein is reported as exclusive of the Mineral Reserve before dilution and other factors are applied, unless otherwise stated. Mineral Resource is subdivided and reported, in order of increasing geoscientific knowledge and confidence, into Inferred, Indicated and Measured Mineral Resource categories. Ounces of gold or silver or pounds of copper, sulphur or molybdenum included in the Inferred, Indicated and Measured Mineral Resource are those contained in situ prior to losses during extraction and processing. While it would be reasonable to expect that the majority of Inferred Mineral Resource would upgrade to Indicated Mineral Resource with continued exploration, due to the uncertainty of Inferred Mineral Resource, it should not be assumed that such upgrading will always occur.

If estimations must be revised due to significantly lower commodity prices, increases in operating costs, reductions in metallurgical recovery or other factors, the Mineral Resource or Mineral Reserve may not be mined or processed profitably. In addition, material write-downs of AngloGold Ashanti’s investment in its mining properties may be required, including impacts on goodwill, as well as increased amortisation, reclamation and closure charges. If AngloGold Ashanti determines that certain parts of its Mineral Resource or Mineral Reserve have become uneconomic, this may ultimately lead to a reduction in its reported aggregate Mineral Resource or Mineral Reserve, respectively. Consequently, if AngloGold Ashanti’s actual Mineral Resource and Mineral Reserve is less than current estimates, its business, prospects, results of operations and financial position may be materially impaired.

Pre-feasibility and feasibility studies for undeveloped ore bodies present estimated capital expenditure and operating costs based on anticipated tonnage and grades of ore to be mined and processed. Other factors underlying the estimations include, among others, the predicted configuration of the ore body, anticipated metal recovery rates, and estimated costs of operating and processing equipment and facilities. Actual operating and capital expenditure cost and economic returns on projects may differ significantly from original estimates. Further, it may take many years from the initial phases of exploration until commencement of production, during which time, the economic feasibility of production may change. The Mineral Resource is subject to further exploration and development, and is subject to additional risks, and no assurance can be given that they will eventually convert to Mineral Reserve.

For additional information, refer to Table 1 (Summary Mineral Resource) and Table 2 (Summary Mineral Reserve) to Paragraph (b) of Item 1303 (Summary disclosure) of Regulation S-K, which are in AngloGold Ashanti’s annual report on Form 20-F for the financial year ended 
31 December 2025 filed with the SEC. These summary tables include each class of Mineral Resource (Inferred, Indicated and Measured) together with total Measured and Indicated Mineral Resource, and each class of Mineral Reserve (Probable and Proven) together with total Mineral Reserve. The Mineral Resource at the end of the financial year ended 31 December 2025 was estimated using a gold price of $2,000/oz (2024: $1,900/oz), a copper price of $3.50/lb (2024: $3.50/lb), a silver price of $23.00/oz (2024: $23.00/oz) and a molybdenum price of $12.00/lb (2024: $12.00/lb), unless otherwise stated. The Mineral Reserve at the end of the financial year ended 31 December 2025 was estimated using a gold price of $1,700/oz (2024: $1,600/oz), a copper price of $3.10/lb (2024: $2.90/lb) and a silver price of $19.50/oz 
(2024: $19.50/oz), unless otherwise stated. The net difference between the Mineral Resource and Mineral Reserve at the end of the last completed financial year and the preceding financial year will be detailed for material properties, if applicable, in AngloGold Ashanti’s annual report on Form 20-F for the financial year ended 31 December 2025.

The Mineral Resource exclusive of Mineral Reserve is defined as the inclusive Mineral Resource less the Mineral Reserve before dilution and other factors are applied.